RBI revises deposit interest rate rules: What’s new for investors like you?
Indians are becoming financially literate gradually and they have started to explore financial instruments like equities, mutual funds, bonds, etc. But many Indians still have their money parked in bank fixed deposits.
The Reserve Bank of India has issued a fresh set of amendments, called the Reserve Bank of India (Commercial Banks – Interest Rate on Deposits) Second Amendment Directions, 2026. The new rules come into effect from October 1, 2026, and while they won’t necessarily have any effect on FD interest rates, meaning because of the rule FD interest rates are not going to increase or decrease. The rules pertain to what banks can do when it comes to quoting a rate to you.
Read on to know what has changed and what implications it has for your money.
What exactly has the RBI changed?
On July 30, 2026, the RBI notified changes to its Interest Rate on Deposits Directions, 2025, after a draft notice it had put out for comments in June, following which it had factored in the suggestions of banks and other stakeholders. The central bank has laid out three broad ideas in a framework that it proposes. The ideas are as follows: uniform pricing for similar deposits, mandatory daily disclosure for bulk deposits and a formal mechanism that will allow banks to price bulk deposits differently based on how “sticky” or stable the funds are likely to be.
These rules are applicable to all banks including commercial banks, small finance banks, regional rural banks, local area banks, payment banks and urban cooperative banks. This means any banks that accept deposits from the public are bound by these new rules.
Rule 1: Same deposit, same day, same rate
The first rule is that any customer of a bank opening a similar fixed deposit at their bank on the same day must get the same interest rate, regardless of which branch they walked into or which relationship manager they spoke to.
This rule was brought in because it used to vary slightly from branch to branch. A branch in a city or urban or semi-urban centres would serve a different client base compared to the one in a rural place. So the interest rate for deposit could vary earlier.
So after the new revised rules, that flexibility no longer exists for branches especially for retail deposits. Therefore if you are a depositor in a metropolitan branch or a tier-2 city branch you are entitled to the same interest rate for the same date of opening, amount and tenure.
For the average everyday investor, this is important because it eliminates any kind of discrepancy. It means the rate advertised on the bank’s website is the same rate at which your interest will be calculated. So you do not have to go to the branch for any kind of negotiation or you do not have to be close to the particular branch manager.
Rule 2: Bulk deposits must be disclosed by 10:10 AM
The second rule is related to deposits, especially bulk deposits which are nothing but deposits that are valued Rs 3 crore or more than Rs 3 crore. These types of high value deposits are deposited by businesses, companies, trusts, high net worth individuals, NRIs, etc.
So with respect to these bulk deposits, banks must compulsorily display the interest rates on their official websites by 10 AM every business day. There is a grace period of 10 minutes, meaning, the interest rates for bulk deposits must be displayed latest by 10:10 AM. So whatever rate is displayed on that business day at 10:10 AM must be honoured by the bank branch if any depositor opens a bulk deposit.
This is useful for bulk depositors because the interest rate for bulk deposits has usually been less transparent. The interest rates are usually negotiated between a bank’s treasury desk and the depositor directly. The new rule provides the public a time-stamped reference point and it also minimizes any contradictory verbal quotes and any confusion.
Rule 3: Banks can still price bulk deposits
The third rule is that and the good news for banks is that the banks can still offer different interest rates for bulk deposits. Though it sounds a little technical, it is important to grasp if you handle bulk deposits.
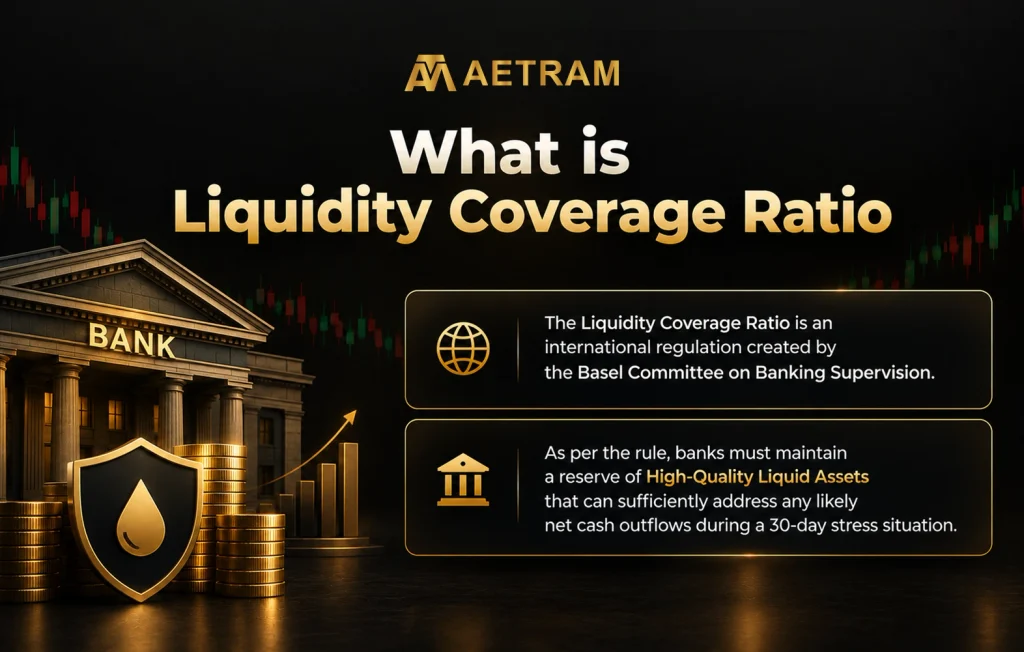
According to the new rule, India’s central bank just linked that flexibility to a particular, quantifiable component called the Liquidity Coverage Ratio (LCR) framework. Rather than totally forbidding institutions from providing varied interest rates on several bulk deposits, the RBI gave a framework for banks to follow.
Under the LCR framework, every deposit or source of financing has a run-off rate. A run-off rate is a metric which tells the bank how probable that money will be withdrawn if the bank comes under financial pressure.
A deposit which is expected to be more stable and less likely to be withdrawn immediately has a lower run-off rate than one considered more flighty.
Banks may now show these variations in the interest rates they provide on bulk deposits, including those from non-resident depositors due to the new amendments. For instance, any two large depositors opening a deposit account for the same amount on the same day could still receive different rates. But the difference will be based on how their money is classified under the bank’s liquidity risk framework, not by some informal negotiation between the branch manager and the depositor or any branch-level discretion.
Will your FD rate go up or down from Oct 1?
Not really, though this is a question that is on every depositors’ mind. The new rules and its implementation is for bringing in transparency and consistency across various deposits and not how banks should set interest rates for its customers.
The banks will continue to set interest rates for individual fixed deposits based on cost of funds, liquidity position, credit demand dynamics, competitive pressures and the broader interest rate cycle.
Any depositors having any existing FDs with any bank will remain unaffected. So the interest rate that was promised for the said tenure will continue unless you prematurely close or break the fixed deposit. However, this new rule will have an impact when depositors start to compare rates offered by different banks before they open new FDs or renew their older deposits. Special rates for senior citizen deposits are unaffected by this change as well, so that pricing segment continues as before.
Important things investors must note
Depositors are expected to be benefited due to the new rules as there will be more transparency and a few groups will feel this more directly. Retail FD investors get an easier way to compare rates across banks without relying on branch-level verbal assurances.
Large depositors and corporate treasuries placing bulk deposits gain from reliable, time-stamped public rate as reference. There will also be clarity on why pricing might differ among various deposits.
Further, NRI depositors placing rupee bulk deposits are explicitly covered under the same LCR-linked pricing flexibility.
Tax professionals and chartered accountants have an additional audit trail for the deposits opened. The disclosed rate schedule on the acceptance date can serve as supporting documentation when verifying a client’s deposit income, interest calculations, or TDS.
What should investors do before Oct 1?
A few practical pointers for investors on how to go about while opening deposits after the new rules kick in.
Always cross-check and verify the rate against the bank’s website before opening a new deposit or or renewing a deposit. Do not just rely on what the employees at the bank branch say.
Your FD maturing today will not auto-renew at the same rate. So always make sure to check the new interest rate before renewing.
Compare interest rates across two or three banks before booking a fresh deposit as the new rules make it simple to compare.
While opening a bulk deposit with a bank branch, enquire if the differential rate is being applied based on LCR run-off framework. Because banks can now rationalise the varying rates on deposits based on this framework.
Always retain a print out or soft-copy of the rate sheet on the day you booked a deposit, especially in the case of bulk deposits.
Final thought
The rules brought by the RBI fits into a broader pattern of the central bank on tightening how banks communicate with depositors, following a similar push for clarity in loan pricing and charges over the past couple of years.
The regulator is not trying to influence where interest rates go. That is still a function of monetary policy, liquidity conditions and each bank’s own commercial decisions.
The central bank is only making sure that whatever rate a bank decides to offer, it must be offered fairly and transparently to everyone.
For investors, it is a meaningful measure because investors will not have any confusion while comparing interest rates for various deposits from October 1. But you will have a much easier time finding out exactly what rate you deserve, and holding your bank to it.