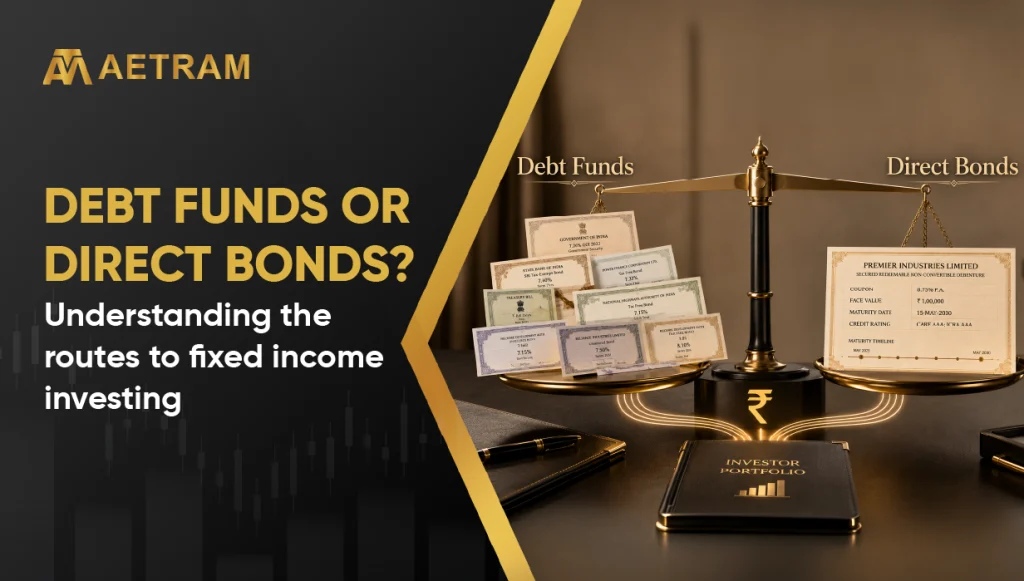
Debt funds or Direct bonds? Understanding the routes to fixed income investing
Indian investors saw fixed income as a separate category for many years. They were unable to tap into the bond market directly. Most Indians invested in fixed income products like fixed deposits, post office savings deposit, provident funds, or maybe one debt mutual fund if one’s advisor recommended it.
This has changed with the RBI’s efforts to widen retail participation in government securities and also the emergence of online bond platforms to give individual investors exposure to corporate paper. “Direct bonds” have now become a viable alternative to debt fund investing.
But which of the two investment avenues is better, for a given investor? The answer depends on their tax bracket, the investment horizon, the willingness to take on responsibility, and the diversification benefits they are willing to forgo in pursuit of higher yields. This blog seeks to describe both paths in detail, so an investor may make an informed choice.
Debt funds: A brief description
A debt fund is a mutual fund scheme that invests in money-market and fixed-income instruments: Government securities, corporate bonds, treasury bills, commercial paper, and certificates of deposit.
Instead of directly buying these instruments, the investor buys units of a mutual fund, whose Net Asset Value (NAV) tracks the value of the portfolio on a daily basis.
SEBI classifies debt funds into roughly sixteen broad categories according to credit quality and tenure. Liquid and overnight funds sit at the lowest risk end of the spectrum, and offer quick parking of idle money.
The central funds are short-duration funds, corporate bond funds, and banking and PSU funds which invest in higher-rated instruments. Further, at the risk-laden end, are credit risk funds, which seek out lower-rated corporate bonds for better returns, albeit with a significantly higher default risk.
Finally, there are gilt funds, which are entirely exposed to the risk of interest rates rising (but do not bear any credit risk).
The advantages of a debt fund are straightforward: Professional management, diversification benefits (a well-constructed fund may hold exposure to dozens of different issuers), and ease of redemption (except for exit loads, these are simple “clicks” away).
Understanding direct bonds
A direct bond purchase means the investor buys a specific debt instrument issued by an entity (the Government of India, a state government, or a company) and holds on to it until maturity or attempts to sell it in the secondary market. Individual investors are now presented with two separate avenues of investing directly in bonds.
The first is the RBI Direct scheme, launched in November 2021. It lets individual investors open a Retail Direct Gilt account directly with the RBI, and invest in Government of India Treasury Bills, dated government securities, State Development Loans, Sovereign Gold Bonds, and RBI Floating Rate Savings Bonds.
There are no account maintenance charges, transaction charges, or brokerage fees, and the minimum investment is a mere Rs 10,000. However, this facility is strictly for investing in Government of India, state government, and Government of India-guaranteed instruments: Tax-free bonds or 54EC capital gains bonds are not available.
The second is Online Bond Platform Providers (OBPPs), SEBI-regulated entities and the online bond segments of the stock exchanges. These let retail investors buy into listed non-convertible debentures (and other corporate bonds) with a minimum ticket size of about Rs 10,000 – Rs 25,000, which used to be the exclusive territory of high-net-worth individuals and institutional players.
Taxation on fixed income securities
For the purpose of taxation, this is the critical difference between a debt fund and a direct bond. Any debt mutual fund units purchased on or after 1 April 2023 will no longer enjoy the benefits of indexation and concessional long-term capital gains treatment.
A redemption of such a scheme’s units on any date, short of 23 July 2024, will be treated as a short-term capital gain under Section 50AA of the Income Tax Act, and taxed at the applicable slab rate. Units purchased before 1 April 2023 and sold after 23 July 2024 will incur a 12.5% long-term capital gains tax, without indexation benefits.
In other words, the taxation of debt funds will now be more or less similar to that of fixed deposits (capital gains tax only upon redemption, not on a yearly basis), but the beneficial indexation provisions which previously made them attractive to higher-tax-slab investors are no longer available.
The taxation of direct bonds differs depending on the class of bond:
- Interest income from a bond (be it a Government of India, state government, or corporate NCD) is taxed on an annual basis as ‘income from other sources’, at the applicable slab rate.
- Gains or losses on redeeming (or selling a listed bond) before maturity are taxed separately: Long-term capital gains tax (12.5%, no indexation) applies to listed bonds held for over 12 months, and short-term capital gains tax (at slab rate) applies to bonds held for less. Sovereign Gold Bonds have long-term capital gains exempt for individual investors if held till maturity, but this exemption does not apply to redemption or secondary-market sales.
Neither bonds nor debt funds enjoy the erstwhile tax advantages anymore. As such, this choice will have to be made on an individual basis, according to an investor’s cash-flow requirements and credit risk appetite.
Liquidity and flexibility comparison
Debt funds have the advantage over direct bonds in terms of liquidity, unless the latter are held in demat form. Open-ended debt funds let the investor liquidate their position on any business day, with proceeds received in one to three working days. Liquid funds even provide facilities for instant redemption, up to a specified limit. Exit load, if applicable, is negligible and tapers off after a few weeks or months.
With RBI Retail Direct, the retail investor may trade in the secondary market via the NDS-OM facility but volumes may be thin and there may be wider bid-ask spread.
Corporate bonds acquired through OBPPs are listed on the exchanges, but many such bonds see little or no trading activity, and the investor may find it difficult to find a buyer.
Direct bonds do have an advantage if the investor is seeking fixed income for a fixed period (i.e., they are seeking to hold on to a bond till maturity). Otherwise, they are at the mercy of market conditions if they need to sell before maturity.
Credit risk and diversification comparison
Debt funds, even relatively risk-averse ones, tend to spread out the risk across twenty to sixty different issuers. A default by one entity will affect the NAV of the fund, but it is unlikely to derail the entire portfolio.
A direct bond purchase concentrates all the risk on one entity. An investor who buys a corporate NCD exposes themselves to the credit risk of the issuing company. Government securities and SDLs are relatively free from credit risk, but corporate bonds need to be evaluated for their credit rating, financials of the issuing entity, and covenants before purchase. This due diligence is performed, or rather paid for, by the fund manager, in the case of a debt fund.
Costs: Expense ratio vs. No costs
Debt funds charge an expense ratio which is likely to reduce the NAV of the fund and therefore the final returns of the investor. This can add up to a significant opportunity cost over a multi-year investment horizon.
The RBI Retail Direct facility charges no account maintenance or transaction charges. OBPPs typically embed their costs in the yield of the bond or levy a very small fee. As such, a direct bond purchase can be significantly cheaper (in terms of expense ratio) than a debt fund, if the investor has the due diligence capability, or is comfortable with the credit profile of the bond (especially government bonds, where credit risk is non-existent).
Which is more suitable?
If an investor is looking for professional credit selection, same-day liquidity and diversification benefits at the cost of some yield and expense ratio, then mutual funds, and particularly liquid, short-duration, or banking and PSU funds, are the way to go for a 1 to 4-year goal.
If an investor has a well-defined horizon that matches a bond’s maturity (or is willing to accept a slightly lower yield for a short-term exposure), and is comfortable with evaluating credit risk (or buying government bonds), direct bonds can offer a cleaner return, free of expense ratios.
Conclusion
The choice between debt funds and direct bonds is no longer an either or scenario, since the erstwhile tax benefits of the former have been stripped away. But which avenue to choose depends on how much control and liquidity the investor is looking for, and how much diversification benefits and costs they are willing to forgo in exchange for yield. Many portfolios these days use both: A debt fund for the liquid part, and direct bonds (government or carefully-vetted corporate) for the buy-and-hold part, to optimize the risk-reward trade-off.
Frequently Asked Questions (FAQs)
1. Is investing in direct bonds safer than debt mutual funds?
Government securities and SDLs carry sovereign backing and are very safe, but corporate bonds bought directly concentrate credit risk in one issuer, unlike a diversified debt fund portfolio.
2. Do debt funds still offer any tax advantage over direct bonds?
Mostly no. Since April 2023, debt fund gains are taxed at slab rates regardless of holding period, similar to bond interest income, removing the old indexation-based advantage.
3. What is the minimum amount needed to invest via RBI Retail Direct?
You can start investing in government securities and treasury bills through RBI Retail Direct with as little as Rs 10,000, with zero account or transaction fees.
4. Can I sell a direct bond before maturity if I need cash urgently?
Yes, through the secondary market, but liquidity varies. Corporate bonds and even retail G-Sec trades can see thin volumes, so exiting early may not always fetch a fair price.
5. Are Sovereign Gold Bonds taxed the same way as other direct bonds?
The capital gains exemption on Sovereign Gold Bonds at maturity applies only if an individual bought the SGB at its original issue and held it continuously through to maturity. This exemption is not available for SGBs bought on the secondary market, nor for those redeemed before maturity.
Disclaimer: The information provided in this article/blog is for educational and informational purposes only and should not be construed as investment, financial, or trading advice. Any financial figures, calculations, projections, examples, or scenarios are hypothetical, intended solely for illustrative purposes, and do not represent actual or future performance. The content is based on information obtained from credible and publicly available sources. While reasonable care has been taken in its preparation, no representation or warranty is made regarding its completeness, accuracy, or reliability. References to indices, securities, or other financial products are for illustrative purposes only. Actual investment outcomes may vary. Investors are advised to carefully read the relevant scheme, circular, or product offering documents and consult a certified and SEBI-registered financial advisor before making any investment decisions. Neither the author nor the publisher shall be liable for any loss, damage, or liability arising from the use of, or reliance on, the information contained in this article/blog.